


Supplemental Health Insurance for Individuals: Plans, Benefits & Limits
Major medical health insurance is designed to help pay for covered healthcare. Explore ACA Marketplace health insurance e private health insurance outside the Marketplace to understand your primary coverage options.
But a serious illness, hospital stay or unexpected accident can create financial consequences that extend beyond the medical bill itself.
A deductible may still need to be paid.
Income may be interrupted.
A family may face transportation, childcare or other everyday expenses while someone recovers.
Supplemental health insurance is designed to address specific financial risks alongside other coverage by paying defined benefits when qualifying events occur.
Common examples include accident insurance, critical illness coverage and hospital indemnity insurance.
These products can provide valuable additional protection in the right circumstances — but they are not substitutes for comprehensive major-medical health insurance.
Questa guida spiega come assicurazione sanitaria complementare for individuals works, the major types of plans, how benefits are paid, what limitations to review and how to determine whether a supplemental policy actually addresses a financial gap you have.
Products, underwriting, benefit amounts, definitions, exclusions and availability vary by insurer and state.
Indice
Risposta rapida: Cos'è l'assicurazione sanitaria complementare?
Supplemental health insurance provides additional benefits for specific covered events or conditions.
Depending on the policy, a benefit may be triggered by:
- an accidental injury;
- a hospital admission;
- diagnosis of a specified serious illness;
- another covered event defined in the policy.
Unlike comprehensive major-medical insurance, many supplemental policies pay predetermined benefits rather than paying the entire actual medical bill.
For certain hospital or fixed-indemnity products, CMS explains that benefits are paid in fixed amounts and consumers may use the cash benefit for medical out-of-pocket expenses or non-medical expenses such as housing costs.
The key idea is:
Major medical coverage helps insure healthcare expenses. Supplemental coverage helps address a specific financial risk associated with a covered event.
What Supplemental Health Insurance Is – and What It Is Not
Supplemental insurance should be viewed as an additional layer of protection.
It may help address costs that comprehensive medical insurance does not fully solve, such as:
- deductibles;
- copayments or coinsurance;
- household expenses;
- transportation;
- childcare;
- other financial consequences of a covered health event.
However, benefit use depends on the actual contract.
It Is Not Automatically Secondary Medical Insurance
People sometimes refer to these products as “secondary insurance,” but that can be misleading.
Traditional secondary major-medical coverage can coordinate medical claims with a primary plan.
Many supplemental policies instead operate under their own benefit schedule and trigger definitions.
A hospital-indemnity policy, for example, may pay a predetermined benefit when a covered hospital event occurs rather than simply paying whatever the primary insurer leaves unpaid.
It Is Not Comprehensive Major Medical Coverage
Supplemental insurance generally does not provide the complete package of protections expected from comprehensive health insurance.
The NAIC distinguishes hospital confinement indemnity, accident-only and specified-disease coverage from comprehensive individual health insurance.
That distinction is essential.
Come funziona l’assicurazione sanitaria complementare passo dopo passo?
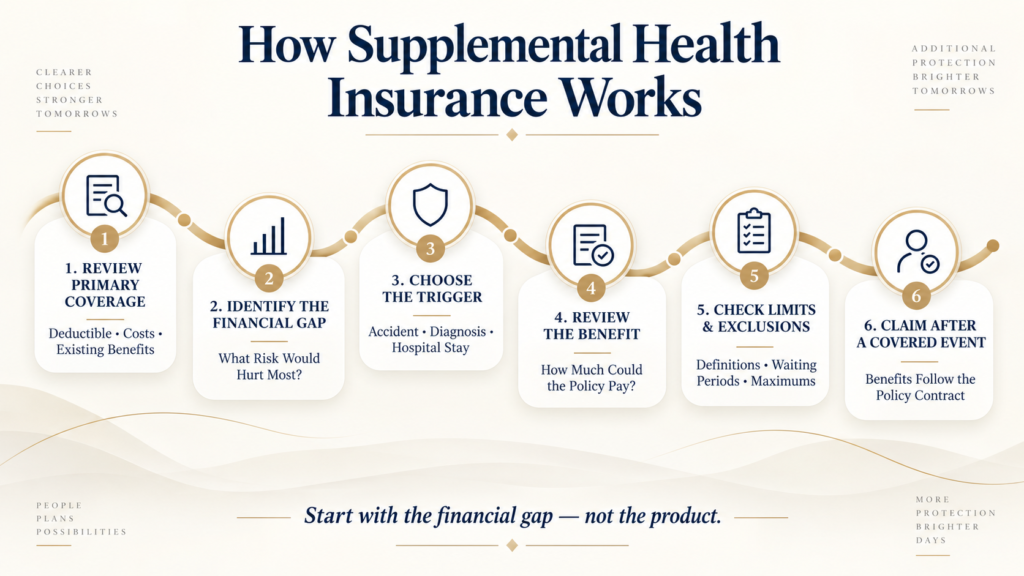
1. Start With Your Existing Health Coverage
Before considering supplemental insurance, understand your major-medical plan.
Recensione:
- deducibile;
- co-pagamenti;
- coassicurazione;
- out-of-pocket maximum;
- benefici ospedalieri;
- assicurazione medica obbligatoria;
- provider network.
You cannot identify a financial gap until you know what your primary plan already does.
2. Identify the Financial Risk You Want to Address
Domanda:
What event would create the largest financial disruption for me?
Possible concerns might include:
- an unexpected accident;
- ospedalizzazione;
- a serious diagnosis;
- time away from work;
- a high deductible.
Do not begin with the product.
Begin with the risk.
3. Choose a Coverage Type That Matches the Risk
Different products use different triggers.
Accident insurance focuses on covered injuries.
Critical illness insurance focuses on qualifying diagnoses.
Hospital indemnity focuses on covered hospital events.
One policy should not automatically be substituted for another.
4. Review the Benefit Schedule
Determine exactly what triggers payment and how much the policy provides.
Look for:
- covered events;
- benefit amounts;
- admission benefits;
- daily benefits;
- diagnosis benefits;
- scheduled injury benefits;
- maximums;
- waiting periods;
- recurrence rules.
5. Review Exclusions and Underwriting
Depending on the product, review:
- medical underwriting;
- pre-existing-condition limitations;
- age requirements;
- waiting periods;
- policy definitions;
- state availability.
Never assume “guaranteed issue” means every condition is automatically covered immediately.
6. Compare the Benefit With the Premium
Ask whether the potential benefit addresses a meaningful financial exposure.
A very inexpensive policy is not automatically valuable.
A policy has value only when the covered trigger and benefit structure match the risk you are trying to manage.
7. File a Claim After a Qualifying Event
When a covered event occurs, claims are evaluated according to the policy.
Supporting documentation may be required.
Benefit payment mechanics vary by product and insurer.
I tre principali tipi di assicurazione sanitaria complementare
Accident Insurance
Accident-only insurance focuses on covered injuries caused by qualifying accidents.
Potential covered events may include items such as:
- fractures;
- dislocations;
- trattamento d’emergenza;
- ambulance services;
- certain diagnostic services;
- other injuries listed in the benefit schedule.
The NAIC describes accident-only coverage as insurance that may provide benefits relating to death, dismemberment, disability or hospital and medical care caused by an accident.
The precise benefit schedule matters.
Two accident policies can have very different definitions and payment amounts.
Accident insurance generally does not cover ordinary illness simply because medical treatment is required.
Critical Illness Insurance
Critical illness insurance is designed around the diagnosis of specified serious illnesses defined by the policy.
Examples may include certain forms or stages of:
- cancer;
- heart attack;
- stroke;
- kidney failure;
- major organ conditions;
- other specifically listed illnesses.
Coverage varies significantly.
The important question is not:
“Does the policy cover cancer?”
È:
“Exactly which diagnosis, severity, definition and conditions trigger the benefit?”
Certain specified-disease and illness policies are recognized under federal excepted-benefit rules when applicable conditions are met.
Critical illness coverage should not be confused with individual disability insurance, which addresses a different financial risk.
A critical illness policy pays based on a covered diagnosis.
Disability insurance generally focuses on loss of qualifying income-earning ability under the policy definition.
Hospital Indemnity Insurance
Hospital indemnity insurance pays defined benefits related to qualifying hospital events.
Depending on the contract, benefits can involve:
- hospital admission;
- days of hospitalization;
- ICU treatment;
- other specified hospital-related events.
CMS describes hospital or fixed-indemnity insurance as paying fixed cash benefits upon qualifying health-related events and emphasizes that these products are not substitutes for comprehensive coverage.
The cash benefit may help with expenses such as:
- a health-plan deductible;
- transportation;
- childcare;
- household expenses;
- other financial needs.
Exactly how and when benefits are paid depends on the policy.
Cosa ne è della polizza per il cancro o per le malattie specifiche?
Some supplemental policies focus specifically on one disease or category of disease.
Cancer insurance is a common example.
These policies can potentially pay benefits when the insured meets the contractual definition of the covered disease.
They should be distinguished from comprehensive health insurance that covers healthcare treatment across a broad range of conditions.
Federal guidance identifies specified-disease coverage, such as cancer-only policies, as one category of independent, noncoordinated excepted benefits when the applicable requirements are satisfied.
A narrow policy may provide meaningful protection for the risk it covers while providing no benefit for an unrelated illness.
Come funzionano i benefici in denaro previsti dalla polizza di assicurazione complementare?
The payment structure depends on the product.
Scheduled Benefit
An accident policy may list predetermined amounts for specified injuries or services.
Lump-Sum Benefit
A critical illness policy may provide a defined lump sum when a covered diagnosis meets the policy requirements.
Hospital Benefit
Hospital indemnity coverage may provide a fixed benefit based on a covered admission, hospitalization period or another contractual trigger.
The amount paid does not necessarily equal your actual medical bill.
That is one of the key differences between these policies and comprehensive major-medical insurance.
In cosa può aiutare l'assicurazione sanitaria complementare?
When a qualifying claim is paid, a supplemental cash benefit may potentially help someone address:
- medical-plan cost sharing;
- transportation;
- childcare;
- household expenses;
- temporary financial disruption;
- other needs permitted by the policy/payment structure.
However, do not purchase supplemental insurance with the assumption that every possible expense will be reimbursed.
The contract determines the benefit — not the amount of financial hardship you experience.
Cosa non copre l’assicurazione sanitaria complementare?
This section is particularly important.
Supplemental coverage generally should not be used as a substitute for comprehensive major-medical insurance.
It may not provide the same:
- broad physician coverage;
- hospital-payment structure;
- prescription benefits;
- rete di fornitori;
- preventive benefits;
- ACA consumer protections;
- annual out-of-pocket protection.
Review the protections and limitations of each policy separately. A fixed cash benefit should not be treated as a guarantee that the full medical bill or any balance remaining after other insurance will be paid.
Come esaminare le informazioni sulle polizze di indennizzo fisso
Before enrolling, read the policy, benefit schedule, exclusions and any consumer disclosures supplied by the insurer. Ask the insurer to explain which events trigger payment, what benefit limits apply and how the coverage differs from comprehensive major-medical insurance.
Do not rely on a marketing summary alone. Request clarification if the advertised benefits do not match the policy documents, and confirm the requirements that apply to the specific product and state before purchasing.
La polizza di assicurazione sanitaria complementare copre le patologie pregresse?
Do not assume that it does.
Depending on the product, insurer and state, coverage may involve:
- medical underwriting;
- pre-existing-condition limitations;
- look-back periods;
- waiting periods;
- esclusioni;
- guaranteed-issue enrollment with limitations.
The rule can differ significantly between accident, critical illness and hospital indemnity coverage.
Always review the actual policy definition before relying on a benefit.
È possibile acquistare un'assicurazione sanitaria integrativa in qualsiasi momento?
Some individual supplemental products may accept applications outside the ACA Marketplace Open Enrollment Period.
But availability is not universal.
It can depend on:
- state;
- insurer;
- product;
- età;
- assicurazione sulla responsabilità civile;
- enrollment channel.
A product being available year-round does non mean it provides comprehensive year-round major-medical insurance.
These are separate questions.
Quanto costa l'assicurazione sanitaria integrativa?
There is no single standard price.
Premiums can depend on factors such as:
- età;
- benefit amount;
- product type;
- individual or family coverage;
- assicurazione sulla responsabilità civile;
- tobacco status where applicable;
- optional riders;
- state;
- insurer.
Instead of asking only:
“How much does it cost?”
ask:
“What covered event triggers the policy, how much will it pay, and what am I paying over time for that protection?”
That produces a more meaningful comparison.
Infortuni vs. Malattie croniche vs. Assistenza ospedaliera
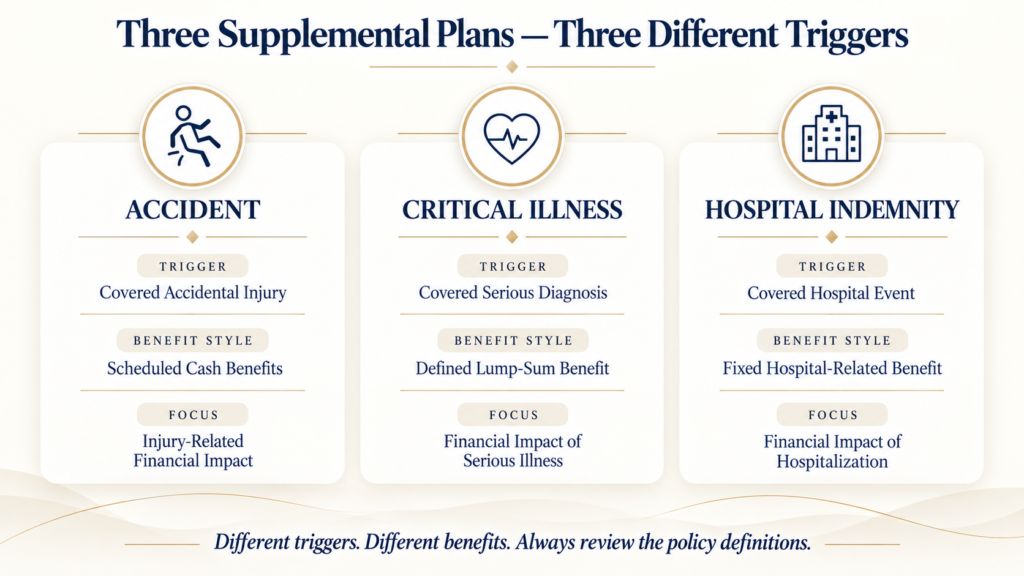
| Copertura | Main Trigger | Typical Benefit Concept | Main Risk Addressed |
|---|---|---|---|
| Accident | Covered accidental injury | Scheduled benefits | Financial effect of an accidental injury |
| Malattia cronica | Covered serious diagnosis | Often lump-sum benefit | Financial effect of specified illness |
| Hospital Indemnity | Covered hospital event | Fixed hospital-related benefit | Financial effect of hospitalization |
These are general descriptions.
Actual definitions, benefits and exclusions depend on the policy.
Recent consumer discussions show exactly why this comparison matters: people frequently ask whether critical illness or hospital/accident coverage is “worth it,” while others report very different experiences depending on the specific event and benefit schedule.
There is no universal winner.
Assicurazione supplementare e piani sanitari a plafond elevato
A person with a high deductible may be particularly aware of financial exposure before the major-medical plan pays a larger share of covered costs.
Supplemental insurance can sometimes be evaluated as one way of addressing a portion of that risk.
But compare the numbers.
Domanda:
- What is my deductible?
- What is my out-of-pocket maximum?
- How much emergency savings do I already have?
- What event triggers the supplemental plan?
- What would it actually pay?
- What does the supplemental premium cost annually?
The goal should not be to “cover the deductible” through marketing language.
The goal is to determine whether the benefit meaningfully improves your financial position.
Assicurazione sanitaria complementare vs. assicurazione per disabilità
These products solve different problems.
Assicurazione sanitaria complementare
Typically pays benefits after a specified covered accident, diagnosis or hospital event.
Assicurazione invalidità
Generally provides benefits when the insured meets the policy’s definition of disability and is unable to earn qualifying income as described in the contract.
A $20,000 critical-illness benefit, for example, does not automatically replace months or years of income.
Likewise, disability insurance does not automatically pay merely because someone receives a serious diagnosis.
They should not be treated as interchangeable.
Chi può prendere in considerazione l'assicurazione sanitaria complementare?
A supplemental policy may deserve evaluation when someone:
- already understands their primary medical coverage;
- has a significant deductible or cost-sharing exposure;
- would have difficulty absorbing the financial consequences of hospitalization, illness or injury;
- wants targeted coverage for a clearly defined risk;
- understands the exclusions and benefit limits;
- can afford the premium without sacrificing more important protection.
Self-employed individuals may also consider the effect that a covered event could have on both medical expenses and household cash flow.
However, supplemental coverage should not automatically take priority over comprehensive health insurance, emergency savings or appropriate disability protection.
Quando un piano supplementare potrebbe non essere la soluzione migliore
It may deserve additional scrutiny when:
- you do not have adequate comprehensive medical coverage;
- you have enough liquid savings to comfortably absorb the specific risk;
- the benefit is too small relative to the premium;
- the event you are concerned about is excluded;
- pre-existing-condition rules significantly reduce usefulness;
- you already have overlapping coverage;
- the plan is being marketed as full medical insurance;
- you do not understand exactly what triggers payment.
An inexpensive policy is still expensive if it never addresses the risk you actually have.
Esemplo pratico
Consider a hypothetical self-employed couple with comprehensive major-medical coverage.
Their health plan has meaningful deductibles and cost sharing.
One partner is concerned that a hospital stay could create two simultaneous problems:
- medical out-of-pocket expenses; and
- reduced business income while recovering.
They evaluate hospital indemnity coverage.
Rather than assuming the policy will “pay the hospital bill,” they review:
- what qualifies as a hospital admission;
- the admission benefit;
- any daily benefit;
- maximum benefit periods;
- esclusioni;
- pre-existing-condition provisions;
- premium;
- how much emergency savings they already have.
They determine whether the scheduled benefit is meaningful enough to justify the cost.
They also separately evaluate disability insurance because a hospital-indemnity benefit is not designed to provide long-term income replacement.
This example is hypothetical and does not represent a quote, recommendation or guarantee of benefits.
Domande da porre prima di acquistare un'assicurazione sanitaria complementare
Before applying, ask:
- What exact event triggers a benefit?
- How much does each covered event pay?
- Is the benefit a lump sum, daily amount or scheduled payment?
- Who receives the payment?
- Is this comprehensive health insurance?
- What conditions are excluded?
- Come vengono gestite le patologie pregresse?
- Is there a waiting period?
- Is there a survival period for certain critical-illness benefits?
- What maximums apply?
- Can the same condition trigger another benefit later?
- Si applicano i criteri di sottoscrizione sanitaria?
- Does the policy cover my spouse or children?
- How long is coverage renewable?
- Can premiums change?
- What happens if I move to another state?
- Does this overlap with insurance I already own?
- How much will I pay each year in premium?
- How does that annual premium compare with the benefit I could reasonably expect?
- Should disability insurance or emergency savings address part of the risk instead?
A clear policy should allow those questions to be answered before enrollment.
Domande frequenti
Vale la pena sottoscrivere un’assicurazione sanitaria complementare?
A volte.
Il suo valore dipende dalla polizza assicurativa, dal livello dei benefici, dalle esclusioni, dalla copertura esistente, dai risparmi per imprevisti e dalla probabilità che il rischio coperto possa causare difficoltà finanziarie.
L'assicurazione sanitaria complementare è davvero un'assicurazione sanitaria?
Si tratta di un'assicurazione, ma molti prodotti aggiuntivi sono non una polizza di assicurazione sanitaria generale.
Offrono benefici limitati o specifici in base al contratto.
L'assicurazione complementare può sostituire l'assicurazione sanitaria dell'ACA?
In generale, i prodotti aggiuntivi come l’indennizzo ospedaliero e la copertura per infortuni non dovrebbero essere presentati come sostituti dell’assicurazione sanitaria integrativa e conforme all’ACA.
L'assicurazione supplementare mi paga in contanti direttamente?
Many supplemental policies provide cash or fixed benefits to the insured or according to the policy’s payment provisions.
Le regole specifiche per i crediti e i pagamenti variano.
Cos'è l'assicurazione per la tutela contro i costi ospedalieri?
Si tratta di una copertura che paga i benefici definiti in caso di eventi ospedalieri previsti.
In genere viene pagato in base al piano dei benefici previsti dal contratto, anziché semplicemente rimborsare l'intero costo dell'ospedale.
What is critical illness insurance?
It generally provides a defined benefit when an insured is diagnosed with a covered serious illness that satisfies the policy definition.
What is accident insurance?
Accident insurance provides specified benefits for qualifying accidental injuries and covered related events.
Is accident insurance the same as health insurance?
No.
Accident-only insurance targets covered accidental events and is not a replacement for comprehensive medical coverage.
Can supplemental insurance cover pre-existing conditions?
It depends on the product.
Some policies may have pre-existing-condition exclusions, waiting periods or other limitations.
Can I have supplemental insurance without major medical insurance?
Product availability may allow this in some circumstances, but owning only supplemental coverage does not provide the broad protection of comprehensive major-medical insurance.
Is supplemental insurance the same as secondary insurance?
Non necessariamente.
Many supplemental plans pay according to their own defined benefit schedule rather than coordinating remaining medical claims like traditional secondary major-medical coverage.
Are supplemental insurance benefits taxable?
Tax treatment can depend on who paid the premiums, how they were paid, the policy structure and the circumstances of the benefit.
Individual tax questions should be reviewed with a qualified tax professional.
Confronta la protezione supplementare con una guida chiara
Supplemental insurance can be useful when it addresses a financial gap you actually have.
The right question is not:
“Which supplemental plan is best?”
È:
“Which financial risk am I trying to manage, and does this policy provide a meaningful benefit when that event occurs?”
A careful review can compare accident, critical illness, hospital indemnity and other available supplemental options alongside your existing medical and income protection.
Comprendere le opzioni di copertura sanitaria supplementare
If you already have major medical coverage and want to understand whether accident, critical illness, hospital indemnity, or other supplemental protection may help address specific financial gaps, request a no-obligation educational conversation.
We can help you compare benefit triggers, exclusions, waiting periods, coverage limits, and how different supplemental options may coordinate with the protection you already have.