


How Do 401(k) and Workplace Retirement Plans Work?
How do 401(k) and workplace retirement plans work? In simple terms, an eligible employee directs part of each paycheck into a retirement account established by an employer. The employer may also contribute, and the account is invested according to the options and rules provided by the plan.
The tax treatment depends on whether contributions are made on a Traditional pre-tax basis, a Roth after-tax basis, or another method permitted by the plan. Investment results are not guaranteed, fees reduce returns, and access to the money is generally restricted because the account is intended for retirement.
This guide explains the most important features for employees, people changing jobs, self-employed professionals, and small-business owners. It is educational and does not recommend a particular investment, rollover, provider, or plan design.
Quick Answer
A 401(k) is an employer-sponsored retirement plan that may allow employees to contribute through payroll deductions, receive employer contributions, select from a plan investment menu, and receive tax advantages under federal law. The plan document determines eligibility, matching contributions, vesting, loans, withdrawals, investments, fees, and distribution options. Other workplace retirement arrangements—including 403(b), 457(b), SIMPLE IRA, SEP IRA, profit-sharing, pension, and cash-balance plans—operate under different rules.
Table of Contents
How Do 401(k) and Workplace Retirement Plans Work Step by Step?
Although plan provisions vary, the basic process usually follows five stages.
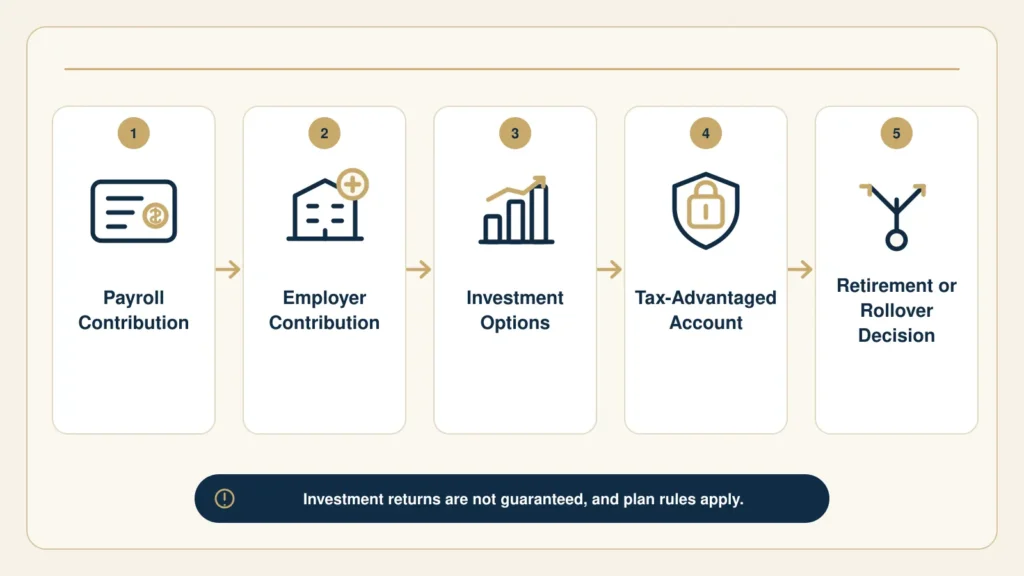
1. The Employer Establishes and Maintains the Plan
The employer adopts a written plan and selects the professionals and service providers needed to administer it. Depending on the arrangement, these may include a recordkeeper, custodian, trustee, third-party administrator, payroll provider, investment fiduciary, ERISA counsel, auditor, and tax professional.
The plan document controls how the plan operates. Marketing materials or informal explanations cannot replace its terms.
2. Eligible Employees Enroll or Are Automatically Enrolled
Employees who satisfy the plan’s eligibility requirements may choose how much of their pay to contribute. Some plans use automatic enrollment, meaning an employee is enrolled at a stated contribution rate unless the employee changes the rate or opts out under the plan’s procedures.
Employees should review the Summary Plan Description, enrollment materials, beneficiary form, investment disclosures, fee information, and employer-match formula before making decisions.
3. Contributions Enter the Account Through Payroll
The employee chooses a dollar amount or percentage of eligible pay, subject to the plan and federal limits. The employer deposits those elective deferrals into the participant’s account. An employer may also make matching, profit-sharing, nonelective, or other permitted contributions.
Employee elective deferrals are always fully vested. Employer contributions may be immediately vested or may become vested over time, depending on the plan.
4. The Participant Selects Investments From the Plan Menu
A 401(k) is not itself an investment. It is a tax-advantaged retirement account that holds investments selected from the choices made available by the plan. Those choices may include target-date funds, mutual funds, collective investment trusts, stable-value options, bond funds, company stock, or other permitted investments.
Account value can increase or decrease. Tax advantages do not prevent market losses.
5. The Participant Eventually Takes a Distribution or Makes a Rollover Decision
Money may remain in the plan until retirement, be paid under the plan’s distribution provisions, or potentially be moved after a qualifying event. When someone leaves a job, available choices may include leaving the account in the former employer’s plan, transferring it to a new employer’s plan, rolling it to an IRA, or taking a taxable distribution.
Each option can affect fees, investments, services, creditor protections, access rules, taxes, and future required distributions. A rollover should never be presented as automatically necessary or automatically superior.
The IRS 401(k) Plan Overview describes a 401(k) as a qualified plan that allows an employee to elect to have part of the employee’s wages contributed to an individual account.
What Is a 401(k) Plan?
A 401(k) is a defined-contribution retirement plan sponsored by an employer. The participant’s eventual benefit is based on contributions, investment performance, fees, withdrawals, and the plan’s rules—not on a guaranteed retirement-income formula.
This is different from a traditional defined-benefit pension. A pension generally promises a benefit calculated using a formula, such as compensation and years of service. A 401(k) instead maintains an individual account for each participant.
Important parties may include:
- Plan sponsor: The employer or organization establishing the plan.
- Plan administrator: The person or entity responsible for plan administration.
- Trustee or custodian: The party holding plan assets.
- Recordkeeper: The provider tracking accounts, contributions, transactions, and participant information.
- Participant: An eligible employee or former employee with an account.
- Beneficiary: The person or entity designated to receive the account after the participant’s death, subject to plan and spousal-consent rules.
- Fiduciary: A person or entity exercising discretionary authority or control over plan management, administration, or assets, as defined under applicable law.
Employees should know whom to contact for the Summary Plan Description, current beneficiary designation, fee disclosures, investment information, account statements, and distribution forms.
Traditional 401(k) vs. Roth 401(k)
Traditional and Roth contributions use different tax timing. Neither is automatically best for everyone.
| Feature | Traditional 401(k) | Roth 401(k) |
|---|---|---|
| Contribution treatment | Generally made before federal income tax | Made with after-tax dollars |
| Current taxable income | May reduce current federal taxable income | Does not reduce current taxable income |
| Investment growth | Generally tax-deferred | Potentially tax-free when distribution requirements are satisfied |
| Retirement distributions | Previously untaxed amounts are generally taxable | Qualified distributions are generally federal income-tax-free |
| Income eligibility | No Roth-IRA-style income limit for elective deferrals | No Roth-IRA-style income limit for elective deferrals |
| Required minimum distributions | Generally apply at the applicable age, subject to plan and employment rules | No lifetime RMD generally required for the original owner under current federal rules |
A participant may be able to divide contributions between Traditional and Roth sources if the plan permits. The combined employee deferrals remain subject to the applicable annual limit.
The appropriate mix can depend on current and expected tax brackets, years until retirement, state taxes, cash-flow needs, estate objectives, and future tax law. Because these variables are personal and uncertain, employees should consult a qualified tax or investment professional when the decision is material.
2026 401(k) Contribution Limits
Federal dollar limits can change annually. For 2026, the principal limits include:
| 2026 limit | Amount |
|---|---|
| Employee elective deferral limit | $24,500 |
| General catch-up contribution for eligible participants age 50 or older | $8,000 |
| Higher catch-up for eligible participants ages 60–63 | $11,250 instead of the general $8,000 catch-up |
| General defined-contribution annual-additions limit | $72,000, generally before permitted catch-up contributions |
| Compensation limit used for qualified-plan calculations | $360,000 |
These figures do not mean every participant can contribute the maximum. Compensation, plan provisions, participation in more than one plan, nondiscrimination requirements, employer contributions, and other rules may limit the available amount.
The higher catch-up applies only when the participant reaches age 60, 61, 62, or 63 during the applicable year and the plan permits it. In addition, certain higher-paid participants making catch-up contributions in 2026 may be subject to Roth catch-up rules. The plan administrator or tax professional should confirm how these provisions apply.
The IRS announcement of 2026 retirement-plan limits confirms the $24,500 employee deferral limit, the $8,000 general catch-up, and the $11,250 catch-up for eligible participants ages 60–63. Current limits should be reviewed each year rather than copied forward indefinitely.
How Employer Matching Contributions Work
An employer match is an employer contribution calculated according to the plan’s formula. Common structures include a percentage of the employee’s contribution up to a percentage of compensation, but formulas vary significantly.
For example, a hypothetical plan might match 50% of employee contributions up to 6% of eligible compensation. An employee contributing less than the amount needed to receive the full available match would receive less employer money under that formula.
Before choosing a contribution rate, ask:
- What is the exact match formula?
- Which types of compensation are included?
- Is the match deposited each payroll period or calculated later?
- Does the plan provide a year-end true-up?
- Must the employee be employed on a particular date to receive some contributions?
- Is the match immediately vested?
- What happens after a leave of absence or employment termination?
An employer contribution is part of the plan’s compensation structure. It should not be described as guaranteed “free money” without reviewing contribution conditions and vesting.
What Does Vesting Mean?
Vesting determines how much of an account the participant has a nonforfeitable right to keep.
Employee salary deferrals are always 100% vested. Employer contributions may be:
- Immediately vested: The participant owns the full employer contribution when deposited.
- Cliff vested: Ownership becomes 100% after a stated service period.
- Graded vested: Ownership increases gradually according to a schedule.
Leaving employment before becoming fully vested may cause the unvested portion of employer contributions to be forfeited. Employees considering a job change should review their current vesting percentage and the date of the next vesting milestone.
Investment Choices, Diversification, and Risk
The retirement account and its investments are separate concepts. A participant can have a 401(k) account but still make unsuitable or overly concentrated investment selections inside it.
Target-Date Funds
A target-date fund generally adjusts its allocation as the selected retirement year approaches. Funds with the same target year can have different asset mixes, glide paths, risk levels, fees, and underlying investments.
Stock and Bond Funds
Plans may offer domestic stock, international stock, bond, money-market, stable-value, or balanced options. The presence of several funds does not automatically create diversification; holdings can overlap.
Employer Stock
Concentrating retirement savings in employer stock can connect employment income and retirement assets to the same company. Participants should understand concentration risk and any plan restrictions before allocating heavily to one security.
Default Investments
If a participant does not make an affirmative election, contributions may be directed to the plan’s default investment. Default does not mean risk-free, guaranteed, or appropriate for every participant.
Investment choices should be evaluated according to time horizon, risk tolerance, other assets, retirement-income needs, and fees. Insurance professionals who are not properly registered to provide securities or investment advice should not recommend specific securities or allocations.
Why 401(k) Fees Matter
Fees reduce the account balance available to compound over time. Even a difference that looks small annually may become meaningful across a long career.
Workplace-plan costs may include:
- Plan administration and recordkeeping fees.
- Investment-management expenses.
- Individual transaction or service fees.
- Advisory or managed-account fees.
- Loan, distribution, or qualified domestic relations order fees.
- Audit, legal, compliance, or third-party administration costs paid by the plan or employer.
Employees should review the plan’s fee disclosure and the expense ratio for each selected investment. Employers should evaluate both total cost and services received; the least expensive provider is not automatically the most suitable, but costs must be reasonable for the services provided.
The U.S. Department of Labor’s guide to 401(k) plan fees explains how administrative, investment, and individual service fees may affect participants.
Can You Borrow From a 401(k)?
Some plans permit participant loans, but federal law does not require a plan to offer them.
A plan loan is not a withdrawal from a bank account. It creates an obligation that generally must be repaid under the plan’s schedule. Interest paid may return to the participant’s account, but borrowing can still create important risks:
- Borrowed money may be removed from its previous investments.
- The account may miss potential market growth while money is out of the investment allocation.
- Repayments are generally made through payroll or another approved method.
- Employment termination may accelerate or complicate repayment obligations.
- A defaulted or offset loan can become a taxable distribution.
- An additional early-distribution tax may apply unless an exception is available.
Before borrowing, compare the true cost with other financing sources and request a written explanation of repayment, interest, fees, investment treatment, and what happens after leaving the employer.
Hardship Withdrawals and Early Distributions
A plan may permit hardship distributions when the participant has an immediate and heavy financial need that satisfies applicable requirements. Availability and documentation depend on the plan and federal rules.
A hardship distribution can permanently reduce retirement savings. It is generally included in taxable income to the extent it represents previously untaxed money and may also face an additional early-distribution tax unless an exception applies. Hardship distributions generally cannot be rolled over.
Employees should not assume that financial difficulty automatically creates tax-free access. The IRS guidance on hardship distributions should be reviewed together with the plan document and individualized tax advice.
What Happens to a 401(k) When You Leave a Job?
Someone leaving an employer generally has four broad choices, subject to the plan and account circumstances.
Leave the Money in the Former Employer’s Plan
This may preserve access to institutional investments, plan-specific services, creditor protections, or favorable fees. The former employee can no longer contribute through that employer, and small balances may be subject to plan distribution procedures.
Transfer the Balance to a New Employer’s Plan
If the new plan accepts incoming rollovers, consolidation may simplify recordkeeping. Compare investment options, total fees, withdrawal rules, loan availability, services, and protections before transferring.
Roll the Balance to an IRA
An IRA may offer a broader investment menu and different services. It may also have different fees, creditor protections, advice arrangements, withdrawal rules, and investment risks. Rolling to an IRA is not automatically better than remaining in a workplace plan.
Take a Distribution
A cash distribution may create current income tax and a possible additional early-distribution tax. It also removes money from its tax-advantaged retirement environment.
A direct rollover generally transfers eligible money directly between custodians and avoids the mandatory federal withholding that can apply when an eligible rollover distribution is paid to the participant. If money is paid to the participant, a 60-day rollover rule and withholding requirements may apply.
The IRS rollover guidance and IRS employment-termination overview describe these choices and important tax rules.
Required Minimum Distributions
Under current federal rules, retirement funds generally cannot remain indefinitely in Traditional tax-deferred accounts.
Required minimum distributions commonly begin at age 73, although an eligible participant in an employer plan may be able to delay them until retirement if the plan permits and applicable requirements are satisfied. Different rules can apply to owners, beneficiaries, inherited accounts, and future birth cohorts.
Designated Roth accounts in 401(k) and 403(b) plans are generally not subject to lifetime RMDs for the original owner under current rules. Beneficiaries remain subject to inherited-account requirements.
Because missed RMDs can create excise taxes, participants should verify the correct beginning date with the plan administrator and a tax professional. See the IRS Required Minimum Distribution guidance.
Types of Workplace Retirement Plans
The appropriate plan depends on the employer, workforce, organization type, budget, desired contribution flexibility, administrative capacity, and tax objectives.
| Plan type | Common setting | Who contributes? | Important distinction |
|---|---|---|---|
| 401(k) | Private-sector employers | Employees and potentially employers | Payroll deferrals, potential match, investment menu and ERISA requirements |
| Safe Harbor 401(k) | Employers seeking a design that can avoid certain annual nondiscrimination tests | Employees and required employer contributions | Employer safe-harbor contributions are generally fully vested |
| SIMPLE 401(k) | Qualifying small employers | Employees and required employers | Simpler structure with lower contribution limits and specific eligibility rules |
| Solo 401(k) | Self-employed owner with no common-law employees other than a spouse | Owner as employee and employer | Can allow employee deferrals and employer contributions, subject to rules |
| 403(b) | Certain public schools, churches, and tax-exempt organizations | Employees and potentially employers | Organization eligibility and investment rules differ from 401(k) plans |
| 457(b) | State/local governments and certain tax-exempt employers | Employees and potentially employers | Distribution and catch-up provisions can differ significantly |
| SIMPLE IRA | Eligible small employers | Employees and required employers | Easier administration but different limits, contribution rules, and early-distribution treatment |
| SEP IRA | Employers and self-employed individuals | Employer contributions | Generally no current employee salary deferrals under a standard SEP |
| Profit-sharing plan | Businesses seeking discretionary employer contributions | Employer | Contributions follow the plan’s allocation formula and applicable limits |
| Defined-benefit or cash-balance plan | Employers seeking formula-based retirement benefits | Primarily employer | Funding obligations and actuarial administration are more complex |
The IRS Retirement Plans FAQ links to the federal rules for major plan types.
Workplace Retirement Plans for Small-Business Owners
Choosing a plan for a small business is not simply a question of finding the highest contribution limit. The employer must consider the entire workforce and the obligation to operate the plan consistently. Employers reviewing a broader benefits strategy can also explore our employee supplemental benefits overview for additional workplace coverage considerations.
Important questions include:
- How many employees are eligible now, and how may the workforce change?
- Does the owner want employee salary deferrals?
- Will employer contributions be mandatory, discretionary, or matching?
- How predictable is business cash flow?
- What contribution level can be sustained during weaker years?
- How much administration and annual testing is acceptable?
- Will a third-party administrator or bundled provider be used?
- What fiduciary responsibilities remain with the employer?
- What startup and ongoing tax credits may be available?
- Will payroll integrate accurately with the recordkeeper?
- How will employees receive education without individualized unlicensed investment recommendations?
Traditional 401(k)
A Traditional 401(k) offers broad design flexibility but may require annual nondiscrimination testing and more administration.
Safe Harbor 401(k)
A Safe Harbor 401(k) generally requires specified employer contributions that are fully vested. In exchange, the plan can avoid certain testing requirements when all conditions are satisfied.
SIMPLE IRA or SIMPLE 401(k)
These plans may reduce administrative complexity for eligible small employers but use required employer contributions and different employee limits and distribution rules.
SEP IRA
A SEP can be relatively straightforward for a self-employed person or employer making employer-funded contributions. Contributions for eligible employees must follow applicable uniformity requirements.
Solo 401(k)
A one-participant 401(k) may fit an owner-only business or an owner-and-spouse business with no other eligible common-law employees. Hiring employees can change eligibility, testing, administration, and plan-design obligations.
Defined-Benefit or Cash-Balance Plan
These designs may permit substantial contributions for some businesses but bring actuarial funding commitments, higher costs, and more complex administration. They require specialized professional analysis.
The Department of Labor’s 401(k) Plans for Small Businesses and the IRS small-employer retirement resources provide official starting points.
Employer Responsibilities and Fiduciary Oversight
Offering a workplace retirement plan creates ongoing responsibilities. Hiring a provider does not necessarily transfer every duty away from the employer.
Depending on the plan and role, responsibilities may include:
- Acting solely in the interests of plan participants and beneficiaries.
- Following the plan document insofar as it complies with applicable law.
- Selecting and monitoring service providers.
- Evaluating the reasonableness of fees.
- Diversifying plan investments when required.
- Depositing employee contributions promptly.
- Delivering required disclosures and notices.
- Maintaining accurate payroll and participant records.
- Completing required filings and testing.
- Establishing prudent processes and documenting decisions.
Employers should identify which provider is responsible for each task and which fiduciary functions remain with the sponsor. An ERISA attorney, third-party administrator, investment fiduciary, recordkeeper, accountant, and payroll provider may address different parts of the plan; no single provider necessarily covers all responsibilities.
401(k) vs. IRA vs. Annuity
These arrangements serve different functions and should not be presented as interchangeable.
| Feature | Workplace 401(k) | IRA | Individual annuity |
|---|---|---|---|
| Established through | Employer | Individual custodian | Insurance company contract |
| Main purpose | Workplace retirement saving | Individual retirement saving | Accumulation or contractual income features, depending on product |
| Contribution source | Payroll deferrals and possible employer contributions | Individual contributions or rollovers | Owner premiums; not an employee deferral plan |
| Employer match | May be available | No | No |
| Investment or crediting choices | Limited to plan menu | Depends on custodian and account | Depends on fixed, indexed, or variable contract |
| Tax treatment | Traditional or Roth sources may be available | Traditional or Roth rules | Tax-deferred growth rules generally apply to nonqualified contracts; qualified annuities follow retirement-account rules |
| Access and restrictions | Controlled by plan and federal law | Controlled by IRA and tax rules | Controlled by contract, surrender schedule, tax law, and optional riders |
| Guarantees | No general guarantee against investment loss | No general guarantee against investment loss | Certain guarantees may be backed by the insurer’s claims-paying ability |
Moving workplace-plan money to an IRA or annuity is a consequential rollover decision. Compare the existing plan with every proposed alternative, including fees, investments, services, surrender charges, guarantees, liquidity, creditor protection, tax treatment, and conflicts of interest. If you are evaluating insurance-based retirement income options, our annuity education and planning overview explains common annuity structures, features, and considerations. Never recommend a rollover solely to generate compensation.
A Practical Employee Example
Assume an employee earns $80,000 and contributes 6% of salary to a 401(k). The employee contributes $4,800 during the year before considering payroll timing.
If the employer hypothetically matches 50% of employee contributions up to 6% of eligible pay, the employer could contribute $2,400, subject to the plan’s exact formula, payroll rules, true-up provisions, and eligibility requirements.
The account would then reflect:
- Employee contributions.
- Employer contributions.
- Investment gains or losses.
- Plan and investment fees.
- Any loans, withdrawals, or distributions.
- The participant’s vested percentage in employer contributions.
This example is educational and does not assume a specific rate of return. A market decline can reduce the account even during a year in which contributions are made.
A Practical Small-Business Example
Consider a professional-services company with an owner and eight employees. The owner wants to save for retirement, improve employee retention, and maintain predictable costs.
A Solo 401(k) would generally not fit because the business has common-law employees. A Traditional 401(k), Safe Harbor 401(k), SIMPLE IRA, or another qualified arrangement might be considered, but the correct design depends on employee eligibility, compensation, turnover, desired employer contributions, testing, costs, and administrative capacity.
Before adopting a plan, the owner should request written comparisons showing:
- Employer contribution obligations under different scenarios.
- Employee and owner contribution opportunities.
- Setup, recordkeeping, administration, investment, and advisory fees.
- Testing and filing requirements.
- Fiduciary services included and excluded.
- Payroll responsibilities.
- Termination or provider-conversion costs.
- Employee education and support.
The business should not select a plan using only the owner’s desired contribution. A qualified plan must operate for eligible employees under its terms and applicable law.
Common 401(k) Mistakes to Avoid
Not Understanding the Employer Match
Employees may contribute too little to receive the available match or misunderstand how the formula and true-up work.
Ignoring Vesting Before Changing Jobs
Leaving shortly before a vesting milestone can mean forfeiting part of an employer contribution.
Treating a Target-Date Fund as Guaranteed
A target-date fund can lose value and may not match an individual’s full financial situation.
Overlooking Fees
Participants may compare investment performance without comparing total costs. Employers may focus on headline administration costs while overlooking participant-paid investment or service fees.
Taking an Unnecessary Cash Distribution
A distribution after leaving a job may create taxes, additional taxes, withholding, and loss of future tax-advantaged growth.
Assuming Every Rollover Is Beneficial
An IRA or annuity can have higher costs, different protections, surrender charges, or conflicts that were not present in the workplace plan.
Borrowing Without an Exit Plan
A participant may take a plan loan without understanding what happens after job loss or employment termination.
Failing to Update Beneficiaries
An outdated beneficiary designation can create unintended results. Marriage, divorce, births, deaths, and estate-planning changes should prompt a review with qualified professionals.
Questions Employees Should Ask
- Am I eligible now, and am I automatically enrolled?
- What percentage of my pay am I contributing?
- Does the plan offer Traditional, Roth, or both?
- What is the employer-match formula?
- Am I receiving the full available match?
- What is my current vesting percentage?
- What investment options do I own?
- What are the expense ratios and account-level fees?
- Is my beneficiary designation current?
- Does the plan permit loans or hardship distributions?
- What happens to an outstanding loan if I leave?
- What distribution and installment options are available?
- When must required distributions begin?
- Who can provide fiduciary investment advice under the plan?
Questions Small-Business Owners Should Ask
- Which plan designs fit the workforce—not only the owner?
- Which contributions are required and which are discretionary?
- What annual testing or safe-harbor rules apply?
- Who serves as trustee, administrator, recordkeeper, and investment fiduciary?
- Which duties remain with the company?
- What are total employer-paid and participant-paid costs?
- How are employee deferrals transferred from payroll?
- What happens if payroll data is incorrect or deposits are late?
- Which reports, filings, notices, and audits are required?
- How will providers be monitored and replaced if necessary?
- What tax credits or deductions may be available?
- How will plan changes affect employees?
Frequently Asked Questions About 401(k) and Workplace Retirement Plans
Can I have more than one 401(k)?
Someone changing jobs or working for multiple employers may have more than one account. Employee elective deferral limits generally apply across applicable plans, so contributions must be coordinated.
Is a Roth 401(k) the same as a Roth IRA?
No. Both use after-tax contributions and may provide tax-free qualified distributions, but contribution limits, employer involvement, investment choices, withdrawal provisions, and other rules differ.
Can I withdraw my 401(k) before age 59½?
The plan may permit distributions after specific events or under specified provisions. Taxable early distributions may face an additional 10% federal tax unless an exception applies. Plan availability and tax treatment are separate questions.
What happens to my employer match when I leave?
The vested portion remains yours. Any unvested employer contributions may be forfeited according to the plan’s terms.
Should I roll my old 401(k) into an IRA?
There is no universal answer. Compare leaving it in the old plan, moving it to a new employer plan, rolling to an IRA, and taking a distribution. Fees, investment choices, services, protections, access rules, and taxes differ.
Is a 401(k) protected from creditors?
Many ERISA-covered plans have significant federal protections, but the application of creditor, bankruptcy, domestic-relations, and federal-tax rules depends on the account and circumstances. Obtain legal advice for a specific concern.
Can a self-employed person open a Solo 401(k)?
Potentially, when the business has no eligible common-law employees other than the owner’s spouse. Business structure, controlled-group rules, affiliated service groups, and future hiring can affect eligibility.
Who regulates workplace retirement plans?
Federal responsibilities may involve the Department of Labor, Internal Revenue Service, and other agencies. State and organizational rules may also apply. Responsibilities differ between tax qualification, fiduciary conduct, securities, insurance, and plan administration.
Final Takeaway
Understanding how 401(k) and workplace retirement plans work requires more than knowing the annual contribution limit. Employees need to understand tax treatment, employer contributions, vesting, investments, fees, access rules, beneficiaries, and job-change options. Employers must also evaluate plan design, workforce impact, administration, service providers, cost, and fiduciary oversight.
The best decision begins with the actual plan documents and a comparison of realistic alternatives. Tax advantages are valuable, but they do not guarantee investment performance or make every rollover appropriate.
Understand Your Workplace Retirement Options
If you are reviewing an existing workplace plan, leaving an employer, or exploring retirement benefits for a small business, schedule a free, no-obligation 15-minute educational conversation.
conversation. We can help you organize the questions to ask and identify when a plan administrator, tax professional, ERISA attorney, or appropriately registered investment professional should be involved.